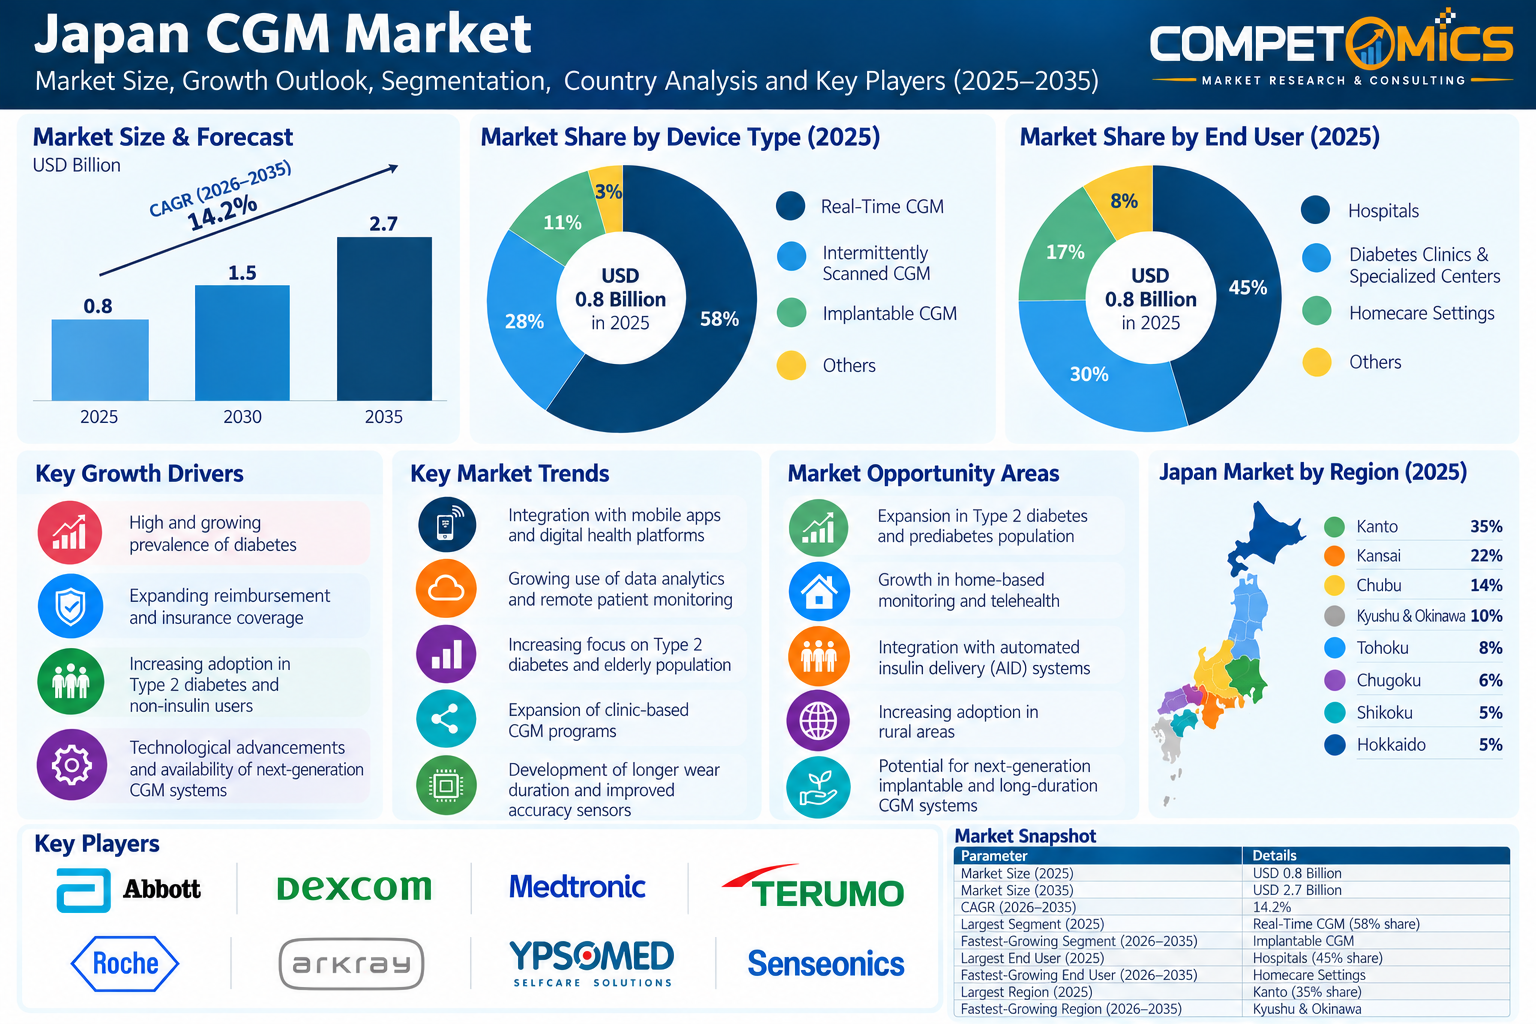
Japan CGM Market was valued at USD 419.29 million in 2025 and is projected to reach USD 1.281 billion by 2035, expanding at a CAGR of 11.81% during 2026-2035. Market expansion is supported by structural demand, technology adoption, increasing healthcare utilization and the need for more convenient, effective or connected solutions. Key opportunities include broader reimbursement and patient access, integration with digital health and automated insulin delivery, and longer-wear, lower-cost sensors and emerging type 2 use.
MARKET VISUALS
Market Overview & Sample Analysis
MARKET VISUALS
Market Overview & Sample Analysis
By Product Type
Sensors are the largest product component because recurring sensor replacement creates the principal revenue pool within CGM systems. Transmitters and receivers represent a smaller share as smartphone-based architectures reduce the need for dedicated hardware. Integrated systems are the faster-growing product opportunity because patients and clinicians increasingly prefer simplified configurations that combine sensing, connectivity and therapy-management capabilities. Longer sensor wear, smaller form factors and easier insertion are reducing friction and can improve adherence. Product competition is therefore moving toward total user experience, not simply measurement accuracy. Local reimbursement and procurement policies influence the mix significantly. In the U.S., broader payer coverage and consumer-oriented models support rapid expansion; in European markets, reimbursement and health-system procurement shape access; in China and Japan, domestic ecosystem development and local market access are increasingly important; and in South Africa, affordability remains a central constraint. The product segment will continue shifting toward integrated, smartphone-connected and lower-maintenance systems.
By Technology
Electrochemical sensing remains the commercial technology foundation because it combines established accuracy with scalable manufacturing and regulatory familiarity. The fastest-moving technology layer is connected CGM, where sensors automatically transmit readings to smartphones and cloud platforms. AI-enabled trend interpretation, alerts and predictive analytics are expanding the value of raw glucose data. Interoperability with insulin pumps is another major growth driver because CGM becomes a control input for automated insulin delivery. Longer-wear sensors, improved adhesives and smaller insertion systems are also important. Non-invasive glucose monitoring remains an emerging opportunity but requires substantial validation before it can displace established minimally invasive systems. In mature markets, technology adoption is increasingly determined by ease of use, reimbursement, data sharing and integration rather than sensor specifications alone. In emerging markets, lower manufacturing cost and simplified distribution are equally important. The result is a two-track innovation pathway: premium connected ecosystems in high-income markets and increasingly affordable, smartphone-compatible CGM products in broader patient populations.
By End User
Homecare is the largest end-user setting because CGM is designed primarily for continuous personal monitoring and because smartphone connectivity enables remote review by caregivers and clinicians. Hospitals and diabetes clinics remain important for diagnosis, initiation, education and management of complex cases, but recurring sensor use occurs largely outside institutional settings. Homecare is also the fastest-growing opportunity as reimbursement expands to additional patient groups and as CGM moves beyond intensive insulin users into broader Type 2 diabetes management. Country differences are pronounced. The U.S. has strong commercial and payer-driven adoption; Germany benefits from established healthcare coverage; Japan combines advanced healthcare infrastructure with an aging population; China has a large addressable diabetes population and expanding domestic device capabilities; Italy is supported by public healthcare and growing awareness; and South Africa faces affordability and access constraints that make lower-cost models particularly relevant. The next phase of market expansion will depend on reducing total cost, simplifying onboarding and linking home-generated data with clinical decision-making.
Region and Country Analysis
North America remains a major revenue center because of high healthcare expenditure, established reimbursement pathways, strong technology adoption and the presence of leading manufacturers. The United States generally drives regional commercialization through early product launches, advanced provider infrastructure and significant private and public healthcare spending. Canada contributes through universal healthcare coverage and technology adoption, although procurement and reimbursement structures differ from the U.S. Europe represents a mature but heterogeneous market. Germany, the United Kingdom, France and Italy combine established healthcare infrastructure with increasing emphasis on cost effectiveness, regulatory compliance and digital health. Market access is influenced by national reimbursement decisions, public procurement and EU-level regulatory requirements. Vendors increasingly compete through lifecycle service, clinical evidence, interoperability and total cost of ownership. Asia Pacific is the key expansion region as healthcare infrastructure improves, chronic disease burden rises, technology awareness increases and manufacturers broaden local distribution. China, Japan, India and South Korea represent important demand centers, but the adoption curve differs substantially by reimbursement, affordability, local manufacturing and clinical practice. Localization, lower-cost product architectures and partnerships with local healthcare providers can therefore create significant opportunities.
Competitive Landscape
The competitive landscape includes multinational manufacturers and specialized technology companies, with Abbott, Dexcom and Medtronic among the most prominent participants in the analyzed market. Their position reflects combinations of installed product base, geographic reach, portfolio breadth, technology investment, distribution capabilities and ecosystem relationships rather than a single competitive factor. Abbott benefits from established scale and portfolio depth; Dexcom has a strong position in product innovation and market expansion; and Medtronic adds complementary capabilities in technology, delivery, monitoring or distribution. Competitive intensity is increasingly shifting from individual products to integrated ecosystems, where software, connectivity, recurring consumables, reimbursement access and clinical support influence customer retention. Smaller specialists and emerging manufacturers can compete through focused technologies, lower-cost models or partnerships. Recent strategic activity among leading participants has centered on product launches, technology integration, interoperability, partnerships and geographic expansion. For this report, the competitive-development chapter will track developments involving Abbott, Dexcom and Medtronic, including qualifying mergers, acquisitions, partnerships, collaborations, product launches, geographic expansions and major product updates. These developments are important because they indicate how leading companies are building ecosystems, extending product lifecycles and entering adjacent segments. Overall, the market is moving toward higher-value, technology-enabled solutions while established products continue to provide a large recurring revenue base. Through 2035, growth is expected to be shaped by affordability, broader access, interoperability, automation and data-driven care. Companies that combine reliable products with digital platforms, evidence generation and efficient distribution will influence the next phase of market development.